Free live workshop
Before You Sign Another Lease
Are you paying thousands every month in rent—and wondering if today's home prices and mortgage rates have made buying impossible?
Give me 60 minutes.
Are you paying thousands every month in rent—and wondering if today's home prices and mortgage rates have made buying impossible?
Wednesday, October 7, 2026
7:00 PM ET
Live via Zoom
100 live seats only
Reserve your seat
Free live HomeBucks workshop
Wednesday, October 7, 2026
7::00 PM ET
Live via Zoom
100 live seats only
We’ll only email you about this workshop and related HomeBucks resources. Unsubscribe anytime.
You make pretty good money.
So why does it feel like you're getting nowhere?
Maybe you're paying $1,800, $2,000, $2,500 or more every month in rent.
You work. You make decent money. You pay your bills.
But another month goes by. Then another year.
And when you start thinking about buying a home, everything seems to point in the same direction:
Home prices are too high.
Mortgage rates are too high.
The payment will be too high.
So the easiest answer is:
“I'll just wait.”
There's nothing wrong with waiting—if waiting is the right financial decision for you.
But before you make that decision, there's one question I think you deserve to answer:
What could waiting actually cost you?
Let's look at two renters who asked that question.
Meet Daniel & Caleb.
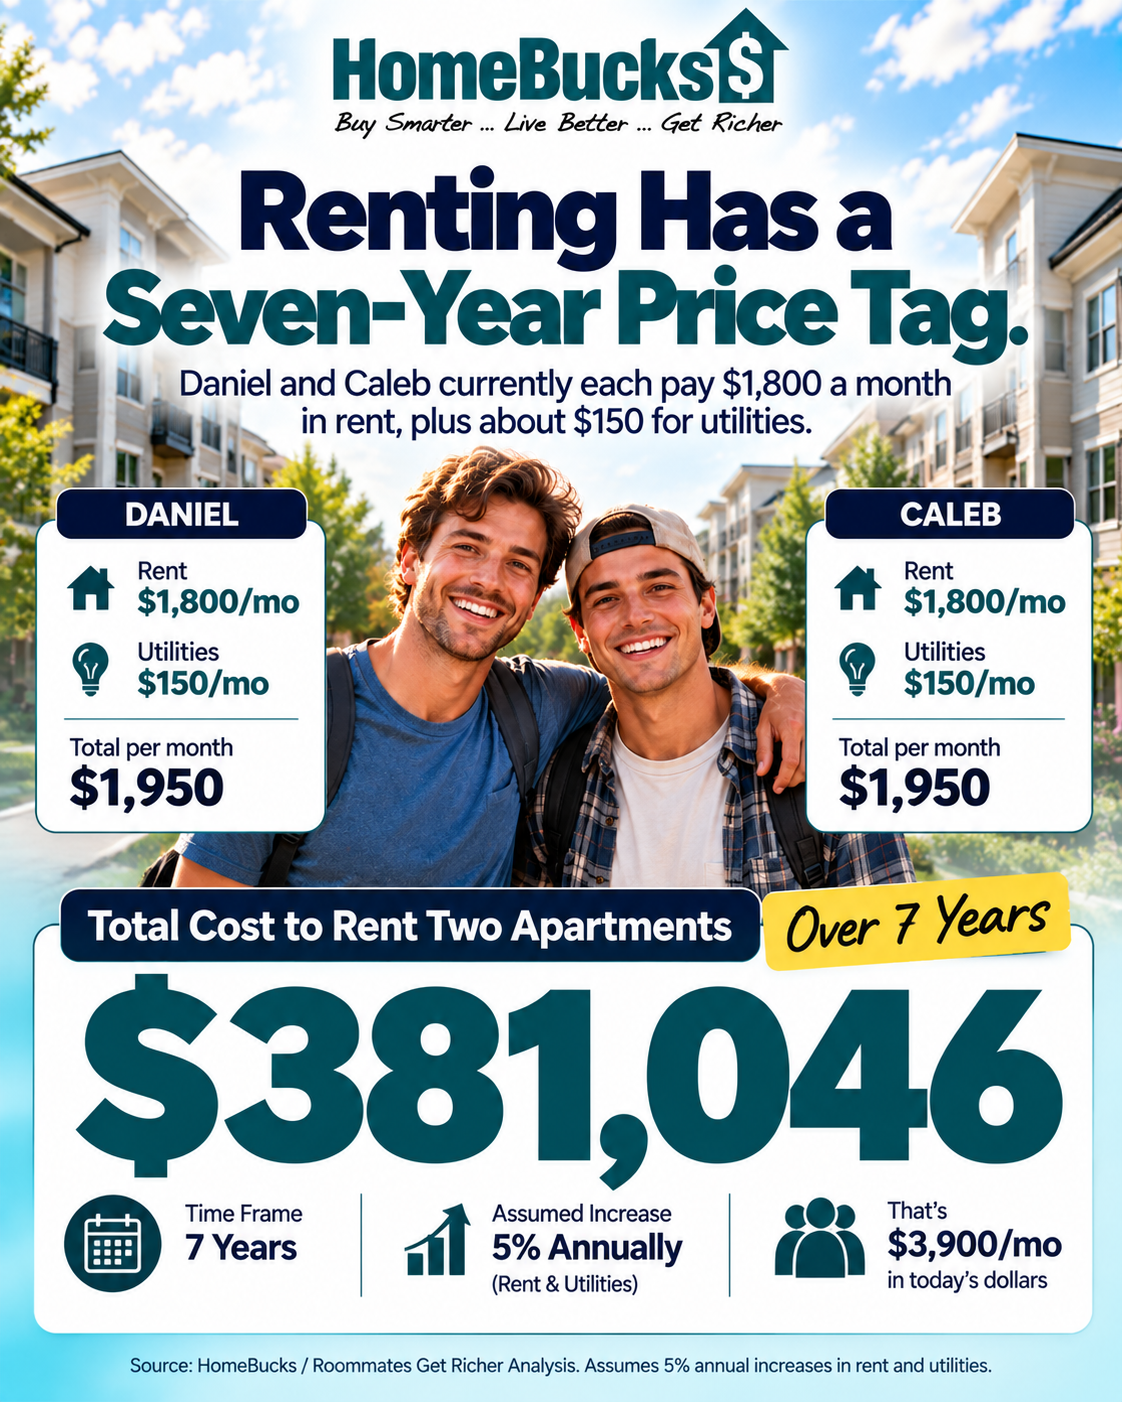
They're 28-year-old former college roommates. Today, they're each spending about $1,950 a month on rent and utilities.
They'd like to own a home.
But with today's home prices and mortgage rates, they wondered how buying could possibly make financial sense.
So we did the math.
But what if we changed the structure?
Instead of renting two apartments, Daniel and Caleb asked a different question:
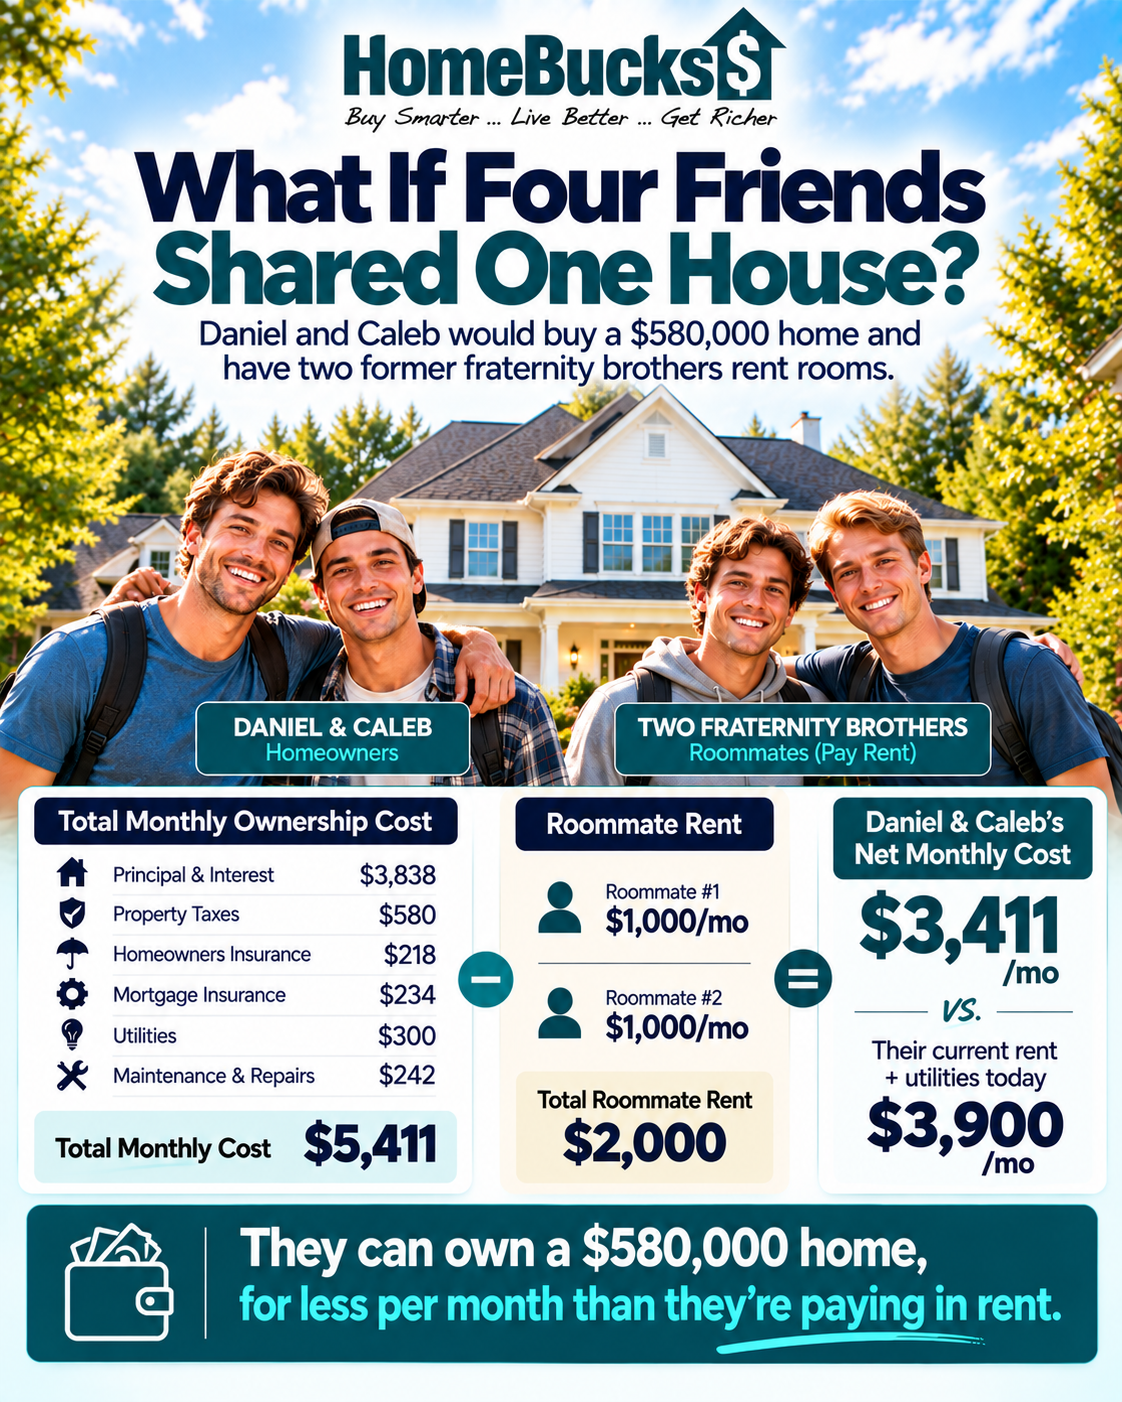
What if we bought one home together—and brought two friends along as roommates?
They're already spending the money.
Daniel and Caleb are currently spending about $3,900 a month on rent and utilities today.
In this scenario, their modeled net monthly housing cost, after their roommate rental income, will be approximately $3,411.
So its actually saving them money to own their home.
But the really interesting part isn't the $489 monthly difference.
It's what could happen over the next seven years.
Case study
How one couple built a model to build an estimated $1,641,000 in additional wealth without earning a dollar more
A couple of our clients, in their early 50s, had a $500K home, a 2.5% mortgage, and $300K in equity.
They came to Kerry while thinking about their next home.
The traditional path was simple: sell the home, cash out the equity, put it down on a bigger house, and take out a new 30-year mortgage at a higher rate.
Instead, Kerry’s Total Wallet analysis looked at the full picture.
The plan modeled how they could eliminate $90,000 in high rate debt, convert their existing home to a long term rental, and redirect over $3,000 per month in freed-up cash flow into wealth-building investments.
Projected result: $1,641,000 in additional household wealth over 15 years.
Not by earning more.
Not by taking wild risks.
By seeing the full picture and making smarter moves at the right stage of the cycle.
Results are illustrative and based on projected scenarios. Individual results vary based on personal financial circumstances, market conditions, and other factors. This is not a guarantee of specific financial outcomes.
Even experienced homeowners can leave real money on the table.
Kerry is currently working with a 57-year-old repeat client who has been through multiple home purchases and refinances over the years.
This client is smart, experienced, and financially aware.
Still, when Kerry ran the Total Wallet analysis, they found foundational credit optimization work that needed to happen first.
That work could help the client qualify for significantly better loan terms on their next move.
This is not beginner-level planning.
It is precision financial planning for homeowners who want to make their next move with more clarity.
This workshop is built for you if:
- You own a home with equity
- You have a mortgage rate below 5%
- You are wondering whether to stay, sell, rent, downsize, or buy again
- You want to help an adult child buy a home without putting your own financial future at risk
- You are thinking about retirement and want your home to support your next chapter
- You want real numbers before making a major housing decision
Only 100 live seats are available.
This is a live Zoom workshop on Wednesday, October 7, 2026 at 12:00 PM ET.
Kerry will present live, walk through the Total Wallet framework, and answer questions in real time.
Capacity is capped at 100 live seats, first come, first served.
If all 100 seats fill, new registrants will be added to the waitlist for the next session.
Reserve My Seat Now - It’s Free 👈Questions? Email [email protected]
Results shared in this workshop are for educational purposes and may include illustrative scenarios. Individual results vary based on personal financial circumstances, market conditions, and other factors. This is not a guarantee of specific financial outcomes.